The Legacy Ledger: Crafting a Family Investment Book to Educate Future Generations
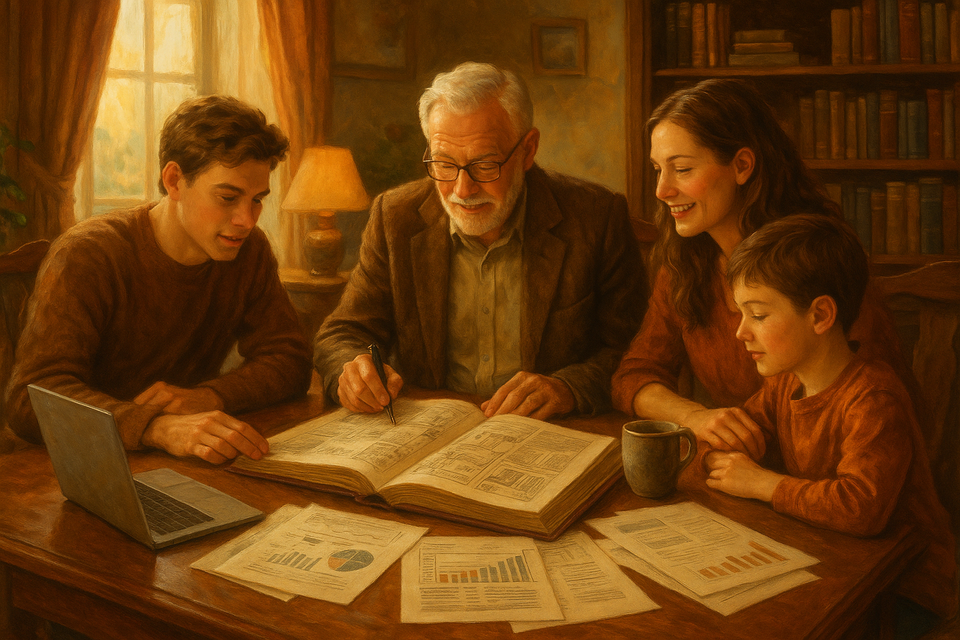
In an era where financial literacy is not just a privilege but a necessity, crafting a family investment book might be one of the most enduring legacies you can leave. A well-structured investment book serves not only as a roadmap for managing wealth but also as a vessel for imparting values and wisdom to future generations. Imagine it as a ledger that records financial strategies alongside the family’s story, seamlessly connecting past, present, and future.
The Purpose of a Family Investment Book
Creating a family investment book essentially serves two major purposes: preserving wealth and instilling values. As pointed out by Standard Chartered Global Private Bank, including philanthropy in the family wealth conversation can strengthen stewardship of wealth and relationships across generations. This perspective encourages families to see beyond mere financial gains and focus on the broader implications of wealth management.
Preserving Wealth
An investment book is a compendium that documents the family’s financial strategies, risks, and opportunities. It’s a framework that guides decision-making, ensuring that wealth is preserved and grown prudently. The book should include diversified investment strategies that have been tested over time, perhaps even embracing concepts like the “general-purpose nerd” approach from Yahoo Finance, where adaptability and continuous learning are emphasized.
Instilling Values
Beyond numbers and returns, the investment book should capture the values that have shaped the family’s legacy. This includes ethical considerations in investments, philanthropy, and community impact—values that renowned legacies like the Rockefellers have embraced, as noted by AOL.com. The investment book becomes a narrative that future members can connect with, understanding the 'why' behind financial decisions.
Structuring Your Family Investment Book
While the content of your investment book will be unique to your family, a structured approach ensures it is comprehensive and accessible. Here's a simplified framework to consider:
- Introduction: Define the purpose and scope of the book. Explain its importance and how it aligns with family values and goals.
- Financial Principles: Document key investment principles, risk tolerance, and financial goals. This becomes the guiding philosophy for all decisions.
- Portfolio Overview: Include a snapshot of current assets, liabilities, and investment allocations. Regular updates are crucial for accuracy.
- Diversification Strategies: Detail the rationale behind various asset classes and geographic diversification. Include lessons learned from past investments.
- Philanthropy and Ethics: Describe the family’s philanthropic goals and ethical investing criteria. Reference the importance of alignment with family ethos, as mentioned by Town & Country Magazine.
- Governance and Roles: Define family roles in investment management and decision-making processes. This helps in avoiding conflicts and ensuring smooth transitions, as family-run businesses often struggle with internal leadership transitions, according to Accounting Today.
Tools and Strategies for Effective Communication
To ensure the book remains a living document, it’s important to integrate tools and strategies that facilitate effective communication across generations. Regular family meetings, as suggested by Insurance NewsNet, can enhance trust and communication. These gatherings are not simply financial check-ins but opportunities for storytelling and connecting values to goals.
Leveraging Technology
Consider digital platforms that make the investment book accessible while maintaining security. Platforms that enable collaboration and feedback can help keep the book relevant and engaging. Think of this as a digital transformation akin to the shift in venture markets highlighted by NatLawReview.com — from static to dynamic.
Educational Initiatives
Incorporate educational elements, like interactive modules or workshops, tailored to different age groups. This ensures that even the youngest family members are engaged in financial discussions early on, setting the stage for responsible stewardship.
Challenges and Pitfalls
Creating a family investment book is not without its challenges. One potential pitfall is the assumption that all family members have the same level of financial literacy. Address this by incorporating educational resources that cater to varying levels of understanding.
Additionally, there may be resistance to change or disagreement on financial principles. Mitigate this by emphasizing the importance of unity and the shared vision for the family’s legacy. Facilitate open discussions that respect diverse opinions without compromising the core values documented in the book.
Conclusion: Crafting a Lasting Legacy
In crafting a family investment book, you are not just creating a financial document; you are forging a narrative that binds your family’s past with the possibilities of the future. It captures lessons learned, values cherished, and the dreams yet to be realized. In doing so, you’re not merely securing financial prosperity, but ensuring that your legacy is one of wisdom, stewardship, and shared purpose.